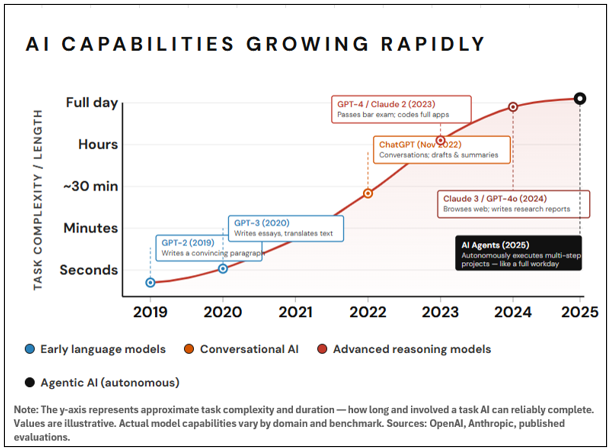
If you love trains, you understand the big difference between knowing a train is due soon and actually seeing the massive engine rounding the bend. For months or even years, artificial intelligence experts have told us to prepare for the arrival of an AI that builds ever more powerful versions of itself. Well, now it’s in sight, horn blaring and ground shaking.
Over the past few weeks, leading AI developers Anthropic and OpenAI have each released new versions with computer programming capabilities that veteran software engineers describe as both astonishing and terrifying. The AI can now do software coding at a level comparable to experts with decades of experience. Soon, its capabilities will zoom past that.
Concurrently, we are told that much of the latest AI was built by the AI itself. This so-called “self-recursive” activity implies ever more powerful AI models, released with increasing frequency.
Productivity Up. Unemployment to Follow?
The most immediate impact of these developments is felt by software coders themselves. Suddenly, they are vastly more productive, as AI can now employ an army of virtual agents to quickly do most of the previously laborious coding work. But this same advance might also make many coders redundant. We read stories of Stanford grads with computer science degrees—once a golden ticket to lucrative employment—facing a more difficult entry level job market.
Of course, AI’s impact doesn’t stop with coders. In a world where almost every business is to varying degrees a technology enterprise, the implications are enormous. Over time, as with technological advances dating back at least to the start of the Industrial Revolution, we can expect AI to take over a wide range of tasks currently performed by humans.
The optimistic take on this envisions a future of greater output and wealth, with employees quickly elevating their work to more valuable activities. The more worrisome outlook is that AI advances quicker than the average worker can adapt, leading to high levels of unemployment. Such impact would be most immediately felt in white collar jobs that are mostly performed on a computer. However, in time, AI-enhanced robotics could replace blue collar workers, too.
AI and Your Investments
The stock market is doing its best to digest all the AI news. We see its verdict rendered in the daily movement of stock prices, much of it very volatile of late. Right now, there are many more questions than answers. Here are a few that are top of mind.
The tech giants (Google, Meta, etc.) are pouring hundreds of billions of dollars annually into building datacenters in a sort of AI arms race that many view as winner-take-all. How will they earn a fair return on these massive investments? And what becomes of the losers in this race?
AI can help companies in many ways, including enabling the creation of new products and services, increasing worker productivity, and reducing labor costs. Will these benefits more than offset the potential reduction in consumer demand resulting from an AI that puts people out of work?
It appears that AI can quickly replicate complex software that may have taken thousands of engineers decades to build and refine. Does this mean AI will ultimately bankrupt countless companies whose primary value resides in their proprietary software?
Economist Joseph Schumpeter coined the phrase “creative destruction” to describe the process by which technological advances lay the groundwork for both the introduction of the better mousetrap and the obsolescence of what came before. With AI, it is very possible we will witness creative destruction of a scale and speed well beyond anything ever experienced.
What is an investor to do in the face of all this? It is impossible to know in advance who the winners and losers will be in the brave new world of AI. The possibility that there will be a very small number of big winners and a much larger number of losers makes the task more challenging still.
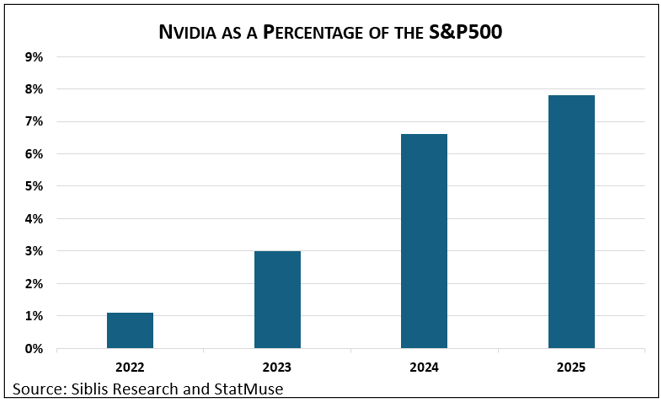
It is wisely said that if you must own the needle in the haystack, you should buy the haystack. Put another way, stay diversified. Index funds—which own the entire market—ensure that you will participate in the growth of the market’s top performers. A prime example is Nvidia, maker of the graphics processors so critical to AI. Its share of the S&P 500 ‘s total value grew from about 1% to well over 7% in just the past three calendar years, which is even more remarkable considering that the index nearly doubled in that timeframe.
It also makes sense to diversify across asset categories, for example, stocks, bonds, real estate, and even perhaps precious metals such as gold. Diversification cannot ensure success. But in the face of AI-fueled rapid change with unpredictable consequences, it might just make failure less likely.
Donald Gould is president and chief investment officer of Gould Asset Management of Claremont.Don is a recurring guest columnist for the Courier, providing his unique insights and observations on matters of money, investing, and personal finance.
Note: This post is an excerpt from Gould Asset Management’s Economic and Market Review for the Fourth Quarter of 2025. The excerpt is posted here for the benefit of our blog subscribers.
Stocks Advance in Q4, Capping a Strong 2025
Global equity markets posted steady gains in Q4, with several major indexes finishing the year near record highs. International stocks outperformed US equities for the first time in several years, aided by a weaker US dollar, more attractive valuations overseas, and rotation away from US tech stocks. Solid earnings growth and expectations central banks would continue lowering interest rates in 2026 supported markets.
US large-cap stocks, represented by the S&P 500 Index, rose 2.7% in Q4 and finished 2025 up a strong 17.9%. Much of the year’s advance was driven by the technology and communication sectors tied to artificial intelligence. Within that group, Alphabet (up 65%) and Nvidia (up 39%) accounted for a disproportionate share of market gains, underscoring the continued influence of a relatively narrow set of leaders.
Sector performance in Q4 highlighted continued shifts in market leadership. Health Care was the strongest performing sector for the quarter, rising 11.7% and finishing the year up 14.6%, while Communication Services gained 7.3% in Q4 and 33.6% year-to-date. Technology posted more modest gains in the Q4 (up 2.3%) but delivered a strong 24.7% return for the year.
US mid and small cap stocks, measured by the Wilshire 4500 Index, were mostly flat in Q4, slipping 0.3%, but ended the year up a 11.9%. After keeping pace with large caps for much of 2025, smaller companies lagged late in the year as investors gravitated toward larger, more established firms amid economic uncertainty.
International stocks were among the strongest performers of 2025, extending gains in the fourth quarter. Developed-market equities rose 4.9% in Q4 and finished the year up 31.2%, while emerging-market stocks gained 4.7% for the quarter and 33.6% for the year. Returns were broad based, with strong performance across Europe, parts of Asia, and emerging markets, supported by improving economic momentum and attractive valuations. A weaker US dollar—down 7.2% in 2025—provided a tailwind for international investors.
Market volatility increased briefly during Q4 but remained contained overall. The VIX Index began the quarter around 16 and spiked above 26 in November amid a brief market sell-off and concerns around interest rate policy. Volatility eased to 15 by yearend, suggesting investors closed 2025 with a steadier outlook.
Fed Rate Cuts Support Solid Q4 for Bonds
US fixed income markets posted modest gains in the fourth quarter, capping the strongest year for bonds since 2000. Short-term Treasury yields continued to decline in Q4 as the Federal Reserve cut its benchmark rate twice by a total of 0.50%. Meanwhile, yields on longer-term Treasurys rose slightly as concerns about significant US fiscal deficits persist. As measured by the Bloomberg US Aggregate Bond Index, US bonds gained 1.1% in the final quarter of 2025, bringing the full-year return to 7.3%.
A sharp steepening of the US Treasury yield curve was a defining feature of both Q4 and 2025 overall. After beginning 2025 at 4.25%, the 2-year Treasury yield, which is highly sensitive to expectations for Federal Reserve policy, declined from 3.60% to 3.47% in Q4. In contrast, the 30-year Treasury yield rose from 4.73% to 4.84% during the quarter, leaving it little changed for the year.
Mortgage backed securities outperformed other fixed income sectors in Q4, returning 1.7% for the quarter and 8.6% for the year. High yield bonds also delivered strong results, gaining 1.6% in Q4 and 8.6% for the year. Long term Treasurys underperformed, returning -1.0% for the quarter and 4.2% for the year.
Happy New Year! We hope this note finds you easing into 2026. For those of us who remember the turn of the millennium, it is hard to believe we have now entered the second quarter of the century.
US Stocks Do It Again
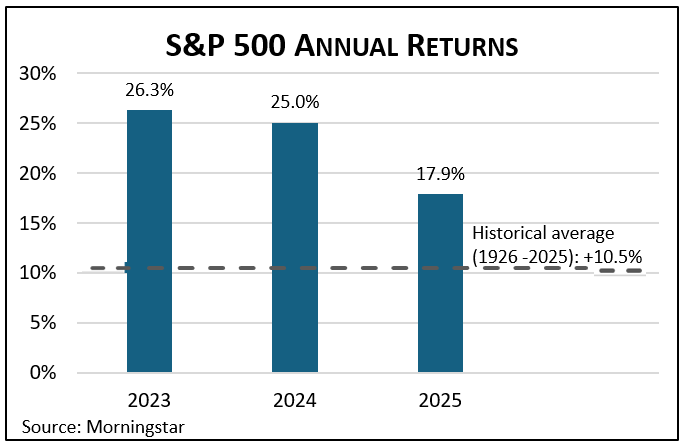
2025 was another banner year for US stocks, with the benchmark S&P 500 up 17.9%—this on the heels of returns of 26.3% and 25.0% in 2023 and 2024. The compound average return for this 3-year stretch is 23.0%, a rate at which money doubles about every 40 months! Over the past century, US large cap stocks have averaged a compound annual return of 10.5%, still terrific, but well below recent experience.
A year ago, we cautioned against expecting these eye-popping returns to continue, though we also noted there was precedent (1997-1999) for the party to continue another year. We will say it again as we enter 2026. Either we are in an unprecedented “new era” of much higher returns (as some AI futurists would suggest) or recent returns are not sustainable. Prior market booms triggered by technological advances—think railroads, electrification, autos, radio, personal computers, biotech, internet—all eventually came back to earth.
We cannot know if this is a new era or just the latest mania, but even as we suspect it’s the latter, we also don’t know when it will end. Faced with this uncertainty, we generally favor regular portfolio rebalancing, selling some of the assets that have risen the most and buying those that have gained the least. And, of course, diversification. These disciplines help keep the market boom from inadvertently pushing clients into portfolios having more risk than intended. But even here, the risk-reduction benefits of rebalancing must be weighed against the often significant tax costs of selling highly appreciated assets.
Foreign Stocks Shine, Gold Glitters
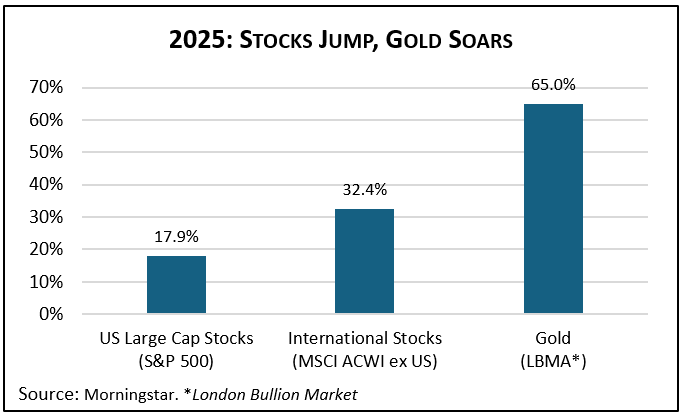
After generally lagging US stocks for many years, foreign stock markets substantially outpaced the US last year, returning about 32% overall and finally rewarding investors for international diversification. More than half the foreign markets’ return edge is explained by a roughly 10% decline in the US dollar, including a 13.3% jump in the euro. To understand this tailwind, consider a laggard German stock that went nowhere in 2025 and started the year worth $1,000. It ended the year worth $1,133, just from the currency effect.
Meanwhile, gold climbed an astounding 65% in 2025, finally surpassing its 1980 all-time high in inflation-adjusted terms. That one ounce coin in your safe deposit box is now worth about $4,500. We think of gold as a hedge against various macro trends, including inflation and geopolitical instability, things we don’t usually associate with outsized stock returns. Yet last year, gold zoomed while stocks flourished. How are we to reconcile this? Any answer is necessarily speculative, but we’ll try a hypothesis.
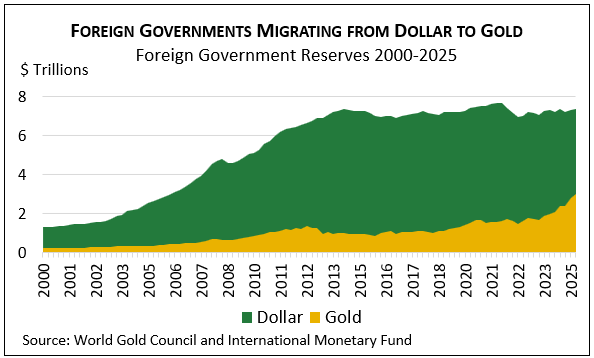
It starts with the historical dominance of the US dollar in the global financial system. For the better part of a century, the dollar has served as the world’s primary reserve currency. Combine this with the substantial policy shifts emanating from Washington since President Trump’s inauguration a year ago and you get big asset price moves. As examples, consider the US decision to impose sweeping worldwide tariffs. Or the conscious weakening of transatlantic alliances, coupled with assertions of US dominance in the Americas. Both policy changes have motivated many foreign governments to diversify their reserves away from the dollar in favor of gold, contributing to a weaker dollar, higher gold prices, and strong foreign stock markets.
Our hypothesis continues with the widely held view that the US is less focused than before on preserving the dollar’s purchasing power. This perception is fed in many ways. Examples include the worsening US fiscal picture, a vicious cycle of persistently large annual budget deficits feeding an ever-growing national debt and interest payments on that debt, in turn further ballooning the deficits. While no one knows what that magic level of US government debt is that causes markets to revolt, debt crises elsewhere have often led to high inflation. Another point of market worry is President Trump’s overt pressure on the Federal Reserve to lower interest rates—this despite inflation currently running nearly a full percentage point above the Fed’s historical 2% target.
Any loss of confidence in the US as a prudent steward of its currency’s value can be expected to drive up the price of assets with a history of preserving purchasing power. These include gold and stocks, especially stocks of companies that can raise their prices to offset inflation. All that said, and perhaps contradicting our own hypothesis, US bonds turned in a strong year amid generally declining interest rates. The leading US bond index gained 7.3%. We will watch this tug-of-war closely.
For a detailed discussion of the economy, financial markets, and investment performance, be sure to see the Q4 Economic and Market Review.
Thank You
As we enter 2026, our 27th year, we manage more than $1 billion for more than 350 clients. We thank you for the trust you place in us daily!
We wish you and yours a healthy, happy, and safe 2026.
How about this for a New Year’s resolution: don’t let anyone steal your money.
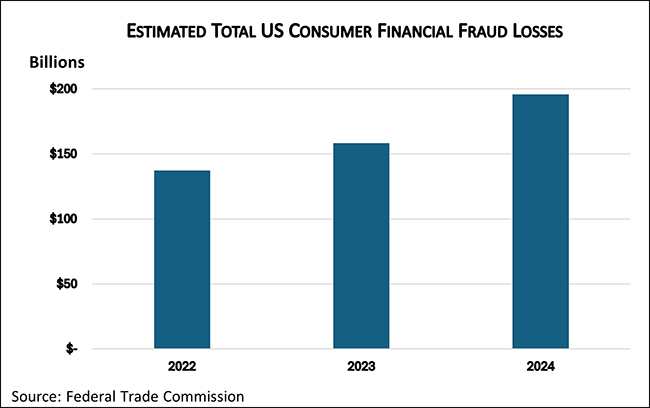
Simple as it sounds, avoiding financial scams gets more challenging by the day. Our electronic financial lives create a bonanza of opportunity for bad actors to separate us from our cash. The scams get ever more clever and sophisticated, with AI opening still new avenues of fraud. The Federal Trade Commission recently released a report estimating that American consumers lost a staggering $196 billion to financial fraud in 2024, a 43% increase in just the previous two years, with older adults losing nearly half the total. If you have been a victim of financial fraud, you are not alone.
A list of dos and don’ts for avoiding scams, while useful, is never quite enough because the landscape of financial fraud is always evolving. I believe a more helpful framework is to understand the psychology of these scams — how they look and feel — so you’ll recognize one when it crosses your path.
The scammer’s secret weapons
Signs that a stranger is trying to steal your money include:
Surprise – You receive a communication (a phone call, an email, a message popping up on your smartphone or tablet, a note on social media, etc.). It usually appears to be from someone authoritative (law enforcement, bank antifraud unit, Microsoft tech support, etc.), but sometimes from someone you know well. Either way, it’s a message you were not expecting when you woke up that morning.
Danger – The communication says you or someone you love is at risk. Your bank account has been compromised. Your grandchild has been arrested and needs bail money. Your computer is infected and exposing you to this or that risk. Your cousin’s passport and cellphone were stolen while traveling abroad and she needs cash to get back home, and so on.
Urgency – You are told time is of the essence. You must act quickly to cure the problem and avoid even greater troubles later.
Secrecy/Paranoia – The scammer implores you not to share this information with anyone. No one can be trusted. Or sharing will embarrass you or someone else.
Combining surprise, danger, urgency, and secrecy is intended to knock you off balance and create a sense of panic—sure ways to compromise your decision making.
Your secret weapon: slow down the process
If you spot any of these signs, the best way to avoid getting scammed is to slow down the entire process. First, just stop the interaction — hang up the phone, end the online chat, don’t reply to the email, ignore the threats. Instead, talk it over with someone you trust. That could be a close friend or relative, or it could be a professional you work with, such as a lawyer, accountant, or financial advisor.
If you find yourself about to do something that you could not have imagined doing when you woke up that morning — for example, buying retail store gift cards, wiring money to a third-party, investing in cryptocurrency, or withdrawing large sums of cash from your bank — again, stop and talk it over with someone you trust.
Consulting with a trusted friend or advisor slows down the process. Your fear and panic subside, you regain your balance, and you’re able to think more clearly. The second set of eyes will help you take a rational approach to addressing the “crisis.” Also, when you bring a second person into the picture, the scammer’s odds of success drop precipitously because now they must fool both you and your friend/advisor.
Taking charge
After regaining your equilibrium, if you still have nagging fears that those urgent warnings might be valid, then take charge of the situation. For example, if you’re worried your bank account might really have been compromised, then independently obtain your bank’s phone number and ask your friend/advisor to do the same. Make sure you get the same number. Then call your bank, explain the situation, and ask if anything is amiss with your account. Or visit a bank branch if convenient.
It is said that a fool and his money are soon parted, but countless unfoolish people daily are the victims of financial theft. With a little preparation, this year you can put the dunce cap on the scammers.
Donald Gould is president and chief investment officer of Gould Asset Management of Claremont.Don is a recurring guest columnist for the Courier, providing his unique insights and observations on matters of money, investing, and personal finance.
We hope this note finds you well. 2025’s home stretch is already upon us.
A Dash of AI Makes for a Strange Economic Brew
The US economy finds itself in a most unusual place. The normal correlation between economic growth and a vibrant jobs market seemingly has disappeared. By most measures, the US economy is expanding at a healthy clip, even faster than its average 2% real (inflation-adjusted) growth rate of the past quarter century. At the same time, jobs growth has slowed to a trickle, with only 22,000 jobs added in August.
AI (artificial intelligence) might explain some of the disparity, in multiple ways. First, massive spending in AI infrastructure (chips, data centers, power facilities) boosts the economy, even while the long-term return on that investment remains uncertain. Second, AI may be fueling productivity gains (higher output per hour worked), meaning some combination of increased growth and reduced employment. Walmart recently forecasted a flat employee count over the next three years, saying it expects AI to affect “literally every job” at the company.
The Federal Reserve last month made its first interest rate cut since the end of 2024, seeing the jobs market challenge as more urgent than subduing inflation, which stubbornly remains above the Fed’s historical 2% target. While lower interest rates tend to stimulate asset prices, it is less clear they will spark jobs growth, especially if AI is the main obstacle to more jobs. We should know the answer soon enough.
Perhaps the current disconnect between economic expansion and employment growth is transitory. Alternatively, it might be the first tangible sign of something AI futurists have long foretold—a world of both rapid economic growth and burgeoning unemployment. Such a world would present significant political and societal challenges.
Notable Market Signposts
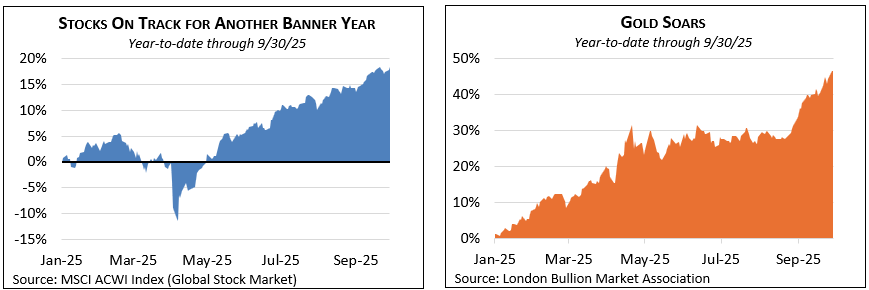
S and international stocks jumped again in the third quarter, with the global equity benchmark rising about 8%, putting markets on course for a third consecutive calendar year of returns substantially above long-term historical averages. For the year to date through quarter’s end, the benchmark S&P 500 was up nearly 15%, while foreign markets returned more than 25%.
And then there’s gold. Alternately labeled a store of value and a barbarous relic, the precious metal is up nearly 50% this year. Remember that gold is an investment that pays no interest or dividends, has no earnings per share, and has real but limited industrial applications. Hence, holding gold entails a significant cost of foregone opportunities. But gold also has managed to maintain its value as a safe-haven “currency” through the centuries, while empires come and go.
We do not see any way to couch gold’s recent ascent as positive news, other than that most of our clients hold some gold in the portfolios we manage. Rather, it is an indication that at some level, even amid a continued bull market, investors are worried. Most likely, they are worried that unsustainable growth in government debt worldwide will threaten the purchasing power of conventional currencies. The tenuous state of today’s politics no doubt intensifies these concerns.
Stock markets are telling a story of optimism, while gold’s message is one of caution. Both can be valid. For a more detailed discussion, be sure to see our quarterly Economic and Market Review that accompanies your quarterly report.
Gould Reaches $1 Billion in Assets Under Management
Last year marked Gould Asset Management’s 25th anniversary, and this year saw us reach another milestone: $1 billion in assets under management! We surpassed that very round number in early September, thanks to continued strong investment returns and new client assets. This accomplishment is only possible because of you, our clients. You have our most heartfelt thanks.