This is the third in a three-part series of reflections on changes in the investment industry in the 25 years since I started Gould Asset Management in Claremont.
Perhaps the most important trait an investor can have is humility, a lesson I’ve been taught repeatedly over the past quarter century. The good news is that if you don’t have humility yet, markets will eventually provide it to you free of charge, except for the hole in your month-end brokerage statement. With humility comes respect for markets, even when you disagree with their verdict.
The Wisdom (and Madness) of Crowds
In his excellent book, The Wisdom of Crowds, James Surowiecki demonstrates that a large group of non-experts, on average, arrives at more accurate estimates than even the most informed expert. Market prices represent the weighted average opinion of a very large crowd at any moment in time, so market “experts” who ignore prices do so at their peril.
Of course, crowds can also be spectacularly wrong. Another investment classic, Charles Mackay’s Extraordinary Popular Delusions and the Madness of Crowds, documents how mass psychology can drive up prices to ridiculous extremes. A famous example is the Dutch tulip mania of 1634-1637. At its height, a single bulb cost more than ten times the annual earnings of a skilled artisan.1
I’ve been thinking about the market crowd even more than usual of late. In the 100+ days since the inauguration, the new administration in Washington has shattered more norms more rapidly than almost anyone might have imagined. However one feels about this, these actions raise important questions for investors. Here are a few of mine.
Some Questions for the Markets…
Immigration. President Trump has pledged to deport more than ten million unauthorized immigrants. Will his plan succeed and, if so, will the workforce shrink, or will citizens fill the gap? And if there are fewer workers, how will that affect labor costs and the inflation rate?
Trade. The president in early April imposed higher tariff rates on scores of countries, notably a 145% rate on imports from China and a 25% rate for Canada and Mexico. A month later, most of the tariffs are on hold, and the China tariff has been temporarily scaled back to 30%, though tariffs remain well above their pre-April levels. Tariffs act as a tax on consumers and businesses, reducing economic activity and raising prices at the same time. Will tariffs, as the president asserts, lead to a resurgence in US manufacturing and raise revenue that will permit tax cuts? Or will tariffs push the US and the world into recession? Or both? And how soon?
Foreign Relations. The past three months have seen some cooling of US relations with traditional allies here in North America and across the Atlantic. Administration actions have raised questions about the longstanding US commitment to defend western Europe against potential Russian aggression. Meanwhile, the president’s oft-stated desire to annex Canada and acquire Greenland have caused tensions closer to home. How might these actions affect economic activity between the US, its neighbors, and western Europe? Will new economic and political alliances emerge as a result? Will a less interconnected America be a more prosperous America?
Higher Education. The new administration has launched an ideological battle with many prominent American universities. Harvard is the most notable example, where the government has frozen billions of dollars of federal research funding and threatened other actions unless the school yields to a series of administration demands. Will cutbacks in university research be permanent? If so, how will this affect discovery and innovation in health care, technology, and other areas? Will this change where top researchers choose to work? And how might this affect the technology entrepreneurship that has powered so much of America’s wealth gains in recent decades?
Larger questions, beyond our scope here, would examine the relationships between financial markets, capitalism, democracy, and the rule of law.
…And Some Tentative Answers
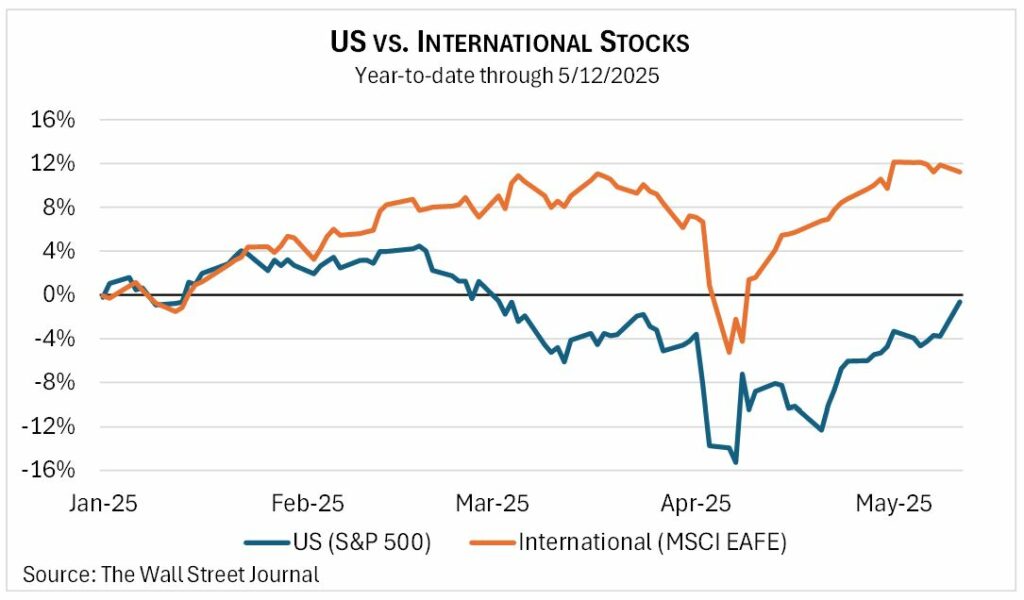
Returning now to the wisdom of the crowd, let’s see how markets might be answering some of these questions. Through May 12, the leading US stock index (the S&P 500) is down about 1% in 2025, though it is up substantially from its initial plunge after tariffs were announced in early April. In contrast, the leading international stock index (MSCI EAFE) is up about 11%, a full 12 percentage points above the US. Fueling the gap is this year’s 6% decline in the US dollar against a basket of foreign currencies. The recent strong relative performance of foreign stocks and currencies runs counter to the most recent 15-year period, during which US stocks and the dollar generally outperformed the rest of the globe.
Explaining market performance is inherently speculative, as we’re trying to read the mind of the crowd, but here goes. In the stock market’s late April recovery, investors might be saying that tariffs will be permanently rolled back to a level that won’t be as damaging as first feared. Meanwhile, strong relative performance of foreign stocks, coupled with dollar weakness, might reflect the view that administration policies more generally will cause US economic interests to suffer.
That’s some of what markets might be telling us today. Tomorrow may be a different story. And even if we could foresee future events, we still would not know with any certainty how markets would respond. So, keep listening to the market’s messages. To paraphrase those clever beer ads, stay humble, my friends—especially when you find the market’s messages most confounding.
Donald Gould is president and chief investment officer of Gould Asset Management of Claremont.
The first quarter of 2025 was unlike any we have experienced. The second Trump administration shattered more norms more rapidly than almost anyone could have imagined. In just over two months we have witnessed the upending of longstanding international alliances through a variety of actions. New tariffs on goods imported from our biggest trading partners, a perceived backtracking of US security guarantees in Europe, and an expressed desire for US annexation of Canada and Greenland are among the headliners. However one may judge these, all will agree we are suddenly living in a changed world, one much different than the post-World War II international order we all grew up with.
Tariffs and Other Storms
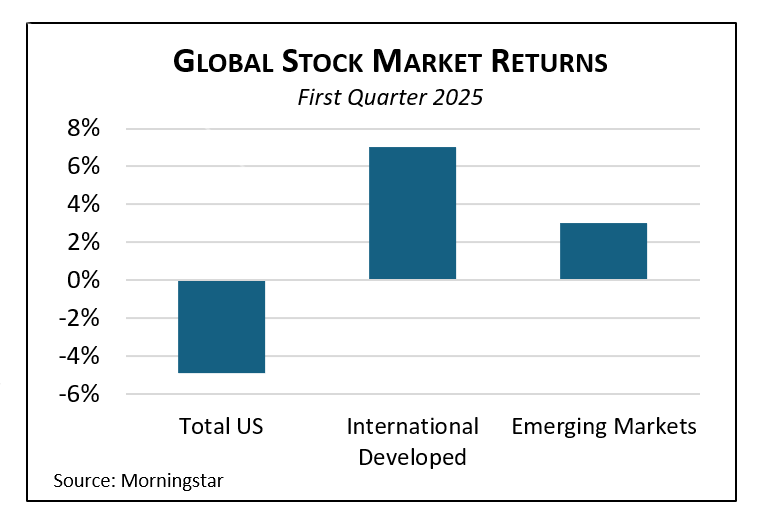
Financial markets reacted negatively, with US stocks substantially underperforming the rest of the globe. The slide accelerated dramatically with President Trump’s April 2nd announcement of unexpectedly large across-the-board tariffs. After dropping 4.3% in the first quarter, the S&P 500 plunged another 10.5% in the two days following the latest tariffs statement. Facing a global stock market rout, a worrisome rise in long-term interest rates, and a weakening US dollar, one week later the president abruptly paused a portion of the tariffs on most countries, and stock markets soared for a day. The US and China remain locked in an escalating trade war, with reciprocal tariffs potentially more than doubling the cost of imports between the two countries.
Tariffs act as a tax on consumers and businesses, reducing economic activity and raising prices at the same time. A slowing economy dents corporate earnings, while higher inflation reduces what investors will pay for those earnings. Both weigh on stock prices. Economists and markets are placing higher odds on a near-term recession in the wake of the new tariffs, though the odds fluctuate with each presidential social media post.
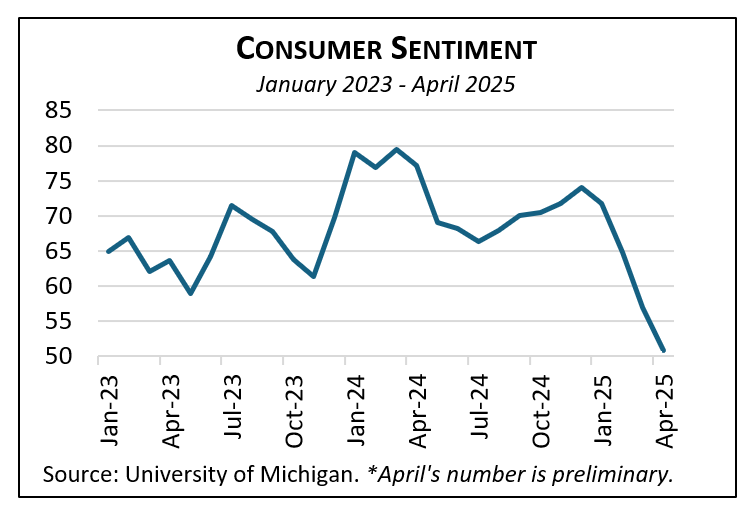
The Fed finds itself in an awkward spot, its hands somewhat tied. The prospect of tariffs challenges both elements of the central bank’s dual mandate of price stability and economic growth. Cutting rates might offset some economic drag from the tariffs, but could worsen the already challenging inflation picture. On balance, recession fears seem to predominate now, with markets now forecasting up to a one percentage point cut in short term rates over the remainder of the year. Well before April’s tariff pinball, consumer sentiment showed a sharp decline in the first quarter.
While our focus understandably is on the financial side of things, we must also acknowledge the unprecedented disruption of the domestic landscape. Multiple US government agencies have been effectively eliminated, while many others are being quickly downsized. Countless new court cases are adjudicating disagreements about the limits of the executive branch’s power within our constitutional system. And there are other shocks to the system too numerous to list. All this has happened less than three months into the new administration’s term. Volatility may be a way of life for some time to come.
Navigating a Whirlwind of Change
We would like to tell you what these tectonic shifts will mean for the world and particularly its financial markets, but there is no road map to consult about the speed and magnitude of change we are experiencing. Investing is about making rational decisions in the face of uncertainty. For us, that means continuing to rely on our investment discipline—principles such as diversification across asset types and regions, asset allocation consistent with client risk tolerance, and periodic portfolio rebalancing.
With great change comes heightened uncertainty about the future and, by extension, elevated investment risk. We are carefully considering the investment implications of the current upheaval and adjusting portfolios as we see appropriate. We are also taking a measured approach. On a boat in a storm, jumping overboard is rarely a sound response.
Note: This post is an excerpt from Gould Asset Management’s Economic and Market Review for the First Quarter of 2025. The excerpt is posted here for the benefit of our blog subscribers.
US Enters 2025 on Uncertain Footing
The US economy expanded at a healthy 2.4% annualized rate in the fourth quarter of 2024, supported by strong consumer spending in the final months of the year. However, first quarter GDP is expected to show a marked slowdown.
The job market looked healthy as of March, before the US announcement of sweeping tariffs. Unemployment ticked up to 4.2% last month, but hiring remained strong. The economy added roughly 152,000 jobs per month in the first quarter, slightly below the 168,000 average for the same period last year. Average hourly earnings grew 3.8% year-over-year in March, cooling a bit from the 4.0% pace in February.
Consumer spending rose 0.4% in February following a drop of 0.3% in January. Spending surged on motor vehicles, furniture, and other durable goods as consumers likely moved up the timing of large purchases to get ahead of looming tariffs. Spending on restaurants and hotels declined as consumers reduced their discretionary expenditures.
US manufacturing activity slipped into contraction territory following two months of expansion. Demand softened and production slowed as input prices surged due to uncertainty surrounding the impact of potential tariffs.
The Fed’s Conundrum
The Federal Reserve held its federal funds rate steady between 4.25% and 4.50% in March, opting for a wait-and-see approach as it assesses the administration’s policy changes on trade, government spending, taxes, and immigration.
The Fed is in a tricky position. New tariffs have raised concerns about a combination of slower growth and rising inflation, a scenario often referred to as stagflation. Fed Chair Jerome Powell noted that economic uncertainty remains high. In its latest projections, the Fed sees growth slowing from 2.1% to 1.7% in 2025, while inflation is expected to rise from 2.5% to 2.8%.
Fed officials projected two 0.25% cuts to the federal funds rate this year, unchanged from their December forecast. This was largely in line with market expectations at the time. However, since the tariff announcements, market participants are now pricing in three to four 0.25% cuts.
Many thanks to those who joined us Tuesday, February 25th, 2025 for Don Gould's live webinar which provided an in-depth update on the current market environment and some of the ongoing challenges facing investors .
Don touched upon quite a few topics which included:
Thanks again to all those who attended. If you have ideas for future topics we should cover or ways we can continue to improve the experience for upcoming broadcasts, please feel free to contact us at contact@gouldasset.com.
We usually kick off this year-end report with a “Happy New Year” greeting. And while we do indeed wish all our clients the very best for 2025, this very young new year has not been a happy one here in our home base of Los Angeles County. Wildfires have destroyed the homes of many clients, business associates, and friends. Others are displaced from their surviving homes for an indefinite period. And virtually everyone in California knows someone severely impacted by the fires. The trauma is both deep and wide. If you have been affected by these terrible fires, please know we are here for you in whatever ways we can help.
A Year of Market Divergences
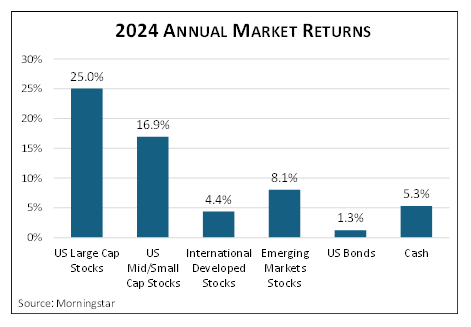
2024 was a good year for most investors despite very mixed performance across asset classes, thanks to another unusually strong year for US large cap stocks. The bellwether S&P 500 returned a whopping 25% last year, leading all major stock categories, so even a moderate allocation there lifted overall portfolio returns. US mid/small cap stocks also did very well, returning nearly 17%, while international developed and emerging markets stocks lagged substantially, gaining only about 4% and 8%, respectively.
Meanwhile, bonds eked out a small gain for the year. Though the Fed cut short-term interest rates, a variety of factors pushed long-term interest rates upward, causing the price of existing bonds to drop. The leading US bond index returned 1.3% , as bond interest income was enough to more than offset price declines.
Lessons for Exuberant Times
The S&P 500’s 25.0% return last year followed a similarly heady 26.3% return in 2023, giving the index its best two-year run since 1997-98 during the nascent internet’s “dot-com” boom. In case you’re wondering, the S&P 500 jumped another 21% in 1999 before peaking in March 2000, from which it shed about half its value in the ensuing 2-1/2 years.
Therein lie lessons. First, we can see that periods of (probably) unsustainably high returns (for example, 20%+/year) tell us very little about what the market will do in the coming year. The 2023-24 party could continue as in 1999, or it could abruptly end as in 2000. The same is true for 2025. Don’t try to time markets.
Second, all booms eventually run out of steam. While the internet was indeed a transformational development, it did not mean infinitely growing profits for businesses benefiting from the new technology. Similarly, AI today offers the possibility of radical change (for better and/or worse), but the combination of competition and finite consumer demand means AI stocks will not become the first proverbial trees to grow to the sky. Don’t get carried away.
We commonly see “recency” bias in how investors evaluate risk. This habit starts early. Company president Don Gould recounts a story from his childhood.
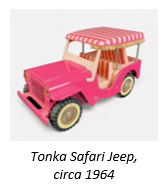
“When I was six years old, the neighbor boy across the street, Walter, invited me over to play with Christmas presents he had just received. Walter’s family had recently moved from Texas to suburban LA, his father a transplanted oil company executive. We were both big fans of the rugged steel Tonka toy trucks, and Walter had struck gold, Santa having delivered the coveted new safari Jeep with its signature candy-striped plastic canopy.
“Walter’s backyard sloped steeply downhill, with a switchback concrete path wending its way through landscaping down to the Rubio Wash, one of LA County’s many flood control channels, at the bottom. Standing at the very top on the back patio, Walter grabbed an older beat-up Tonka jeep of his and gave it a mighty heave down the slope, throwing it like a discus. Miraculously, the jeep landed on the concrete path, squarely on all four tires, unmarred, not unlike an Olympic gymnast “sticking” the landing. Whereupon Walter handed me his new safari jeep and insisted I do the same. Already attuned to concepts of risk and return at that early age, I protested. “You were just lucky with that throw. I’m not gonna throw your new jeep.” Walter would have none of it. The more I resisted, the angrier he got. “It’s MY JEEP and I WANT YOU TO THROW IT DOWN THE HILL!” I suspect my last thought as I let it fly was, yes, it’s your jeep. I’m not sure how or where the safari jeep landed. All I clearly remember is the candy-striped plastic canopy disintegrating upon impact.
“There followed much recrimination, Walter crying over his shattered jeep, me crying over my reluctant role in the disaster, and Walter’s mother Sophie coming out of the house to sort out all the commotion. I pleaded my case, and she wisely sent me home until cooler heads could prevail.”
Walter had understandably concluded from his recent experience that throwing Tonka jeeps was both fun and without much downside risk. Investors often do a similar thing after an extended period of rising stock prices, either underestimating market risk or overestimating their tolerance for the risk.
Investment discipline is the only protection from both our inability to predict the outcome of the market’s next toss and the natural emotions of greed and fear. That discipline includes diversification—today’s winners and losers could quickly swap places—and rebalancing, which helps see that neither bull nor bear markets cause your portfolio to drift away from one that meets your long-term objectives.
What’s Next for Markets
We cannot remember a year-end during which so many have asked our stock market forecast for the coming year. Perhaps it is uncertainty surrounding the change in administration in Washington, but whatever the cause, people seem more curious than usual. We don’t subscribe to the common Wall Street practice of making market forecasts, a futile exercise usually cloaked in a phony aura of expertise and jargon. We have various quips in response to the question of where the market is next headed, such as, “if we knew that, we wouldn’t have to work for a living,” or the more straightforward, “I don’t know."
That said, we can still highlight factors that could help or hurt the stock market in the year ahead. Two stand out. Lower tax rates and lighter regulation—expected outcomes of November’s election results—tend to help corporate profits, a primary driver of stock prices. Many credit this with the stock market’s rise in the first month after the election.
On the converse side, long-term interest rates have moved significantly higher since the election, perhaps indicating concern that we are entering a period of less fiscal restraint, leading to higher deficits, a more rapidly growing national debt, and higher inflation. Higher bond yields are usually (but not always) a drag on stock market performance, and this has been the case for most of December and the first half of January.
The net effect of the two countervailing forces in the ten weeks since the election has been an essentially flat US stock market.
Note: This post is an excerpt from Gould Asset Management’s Economic and Market Review for the Fourth Quarter of 2024. The excerpt is posted here for the benefit of our blog subscribers.
US Stocks Outperform International by Wide Margin in Q4 and 2024
Global stock market performance was mixed in the fourth quarter of 2024, capping off a strong year for many markets. US equities advanced, albeit at a much slower pace than in the first three quarters. Eurozone and Asia markets declined amid concerns over potential new US trade tariffs and political instability in countries like France and Germany.
US large-cap stocks, represented by the S&P 500 index, rose 2.4% in Q4 2024, capping a robust 25.0% gain for the year. After the election, stocks first climbed on expectations of lower taxes and easier regulations, but then gave back gains as those same policy expectations contributed to a jump in long-term interest rates
Consumer Discretionary (up 12.1%) led all US sectors in Q4, finishing the year with a sparkling 26.6% gain on the back of solid consumer spending. Communication Services (up 8.9%) and Technology (up 3.1%) also performed well, and were among the best performing sectors on the year, rising 40.2% and 21.7% respectively. AI was a consistent theme in 2024, driving investor interest and market returns.
US mid and small cap stocks modestly outperformed large caps in Q4, with the Wilshire 4500 stock index rising 4.0% on the period. For the year, US mid and small cap stocks posted strong gains (up 16.9%), but couldn’t keep pace with large caps and the “Magnificent 7” stocks that accounted for more than half of the gains on the S&P 500.
The MSCI EAFE Index fell in Q4 (down 8.1%), finishing 2024 with a modest gain (up 4.4%), impacted by slowdowns in Germany and China, a strong US dollar, and geopolitical uncertainties like potential US trade tariffs. Similarly, the MSCI Emerging Markets Index declined for the quarter (down 7.8%) but rose for the year (up 8.1%), hindered by currency weakness.
Market volatility increased in Q4, due to election uncertainties and policy concerns. The VIX index, a key barometer of market volatility, rose from 16.7 at the start of the quarter to 23.0 around the election, before dropping to 12.7 during a market rally. It later spiked above 28 due to rising bond yields and settled at 17.3 to close 2024.
This is the second in a three-part series of reflections on changes in the investment industry in the 25 years since I started Gould Asset Management in Claremont.
In part one of this series, I described how core investment products such as mutual funds have become commoditized in recent decades, leading to ever lower fees and profits for fund management companies, but commensurately higher returns for their investor clients.
Of course, the Wall Street empire wasn’t going to let disappearing mutual fund profit margins go unanswered. To replace those lost profits, big financial firms have increasingly turned to more complex and less liquid investment products that can command higher fees. These include private equity and private debt funds, which invest in the securities of companies that do not trade on public markets, real estate funds, and so-called “hedge funds” that pursue esoteric trading strategies.
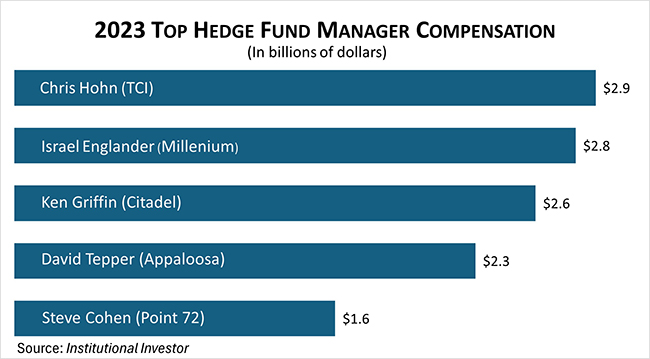
Some of these products are fabulously expensive, which is why you may have read about some hedge fund managers pulling down billions of dollars in annual compensation. It reminds me of the old joke about the tourists visiting lower Manhattan. Their guide points out one financier’s yacht after another. Finally, one rube asks, “Where are the customers’ yachts?”
Enter the index fund:investments get commoditized
The higher the fees on a product, the more skeptical you should be about the value you’ll receive. It is common for private equity and hedge funds to charge a base annual fee of 2% of assets, plus 20% of any profits. These fund managers argue that getting a cut of fund profits gives them an incentive to generate the biggest possible profits for investors.
A more cynical take: this is a one-sided bet squarely in the manager’s favor, not the client’s. If the fund performs great, the manager does extremely well, and the client perhaps does well enough. If instead the fund performs badly, the investor shoulders all the losses.
Don’t get me wrong: these products have their place in a diversified portfolio, but it’s always important to keep an eye on costs. Often, the costs are too high to justify the potential benefits. And sometimes a similar investment can be found in a liquid form at a lower cost.
Innovations: a mixed bag
One of the more useful financial product innovations of recent years are funds whose returns are not highly correlated with either the stock or bond markets. A portfolio reduces risk by including components that don’t all move in the same direction at the same time. That’s the point of diversification.
An example of such a product is catastrophe bonds. (Granted, not the most inviting name for an investment.) These bonds are sold by property-casualty insurance companies looking to off-load some of their risk exposure from, say, an extraordinary major hurricane. “Cat” bonds chalk up steady returns in most years, but face substantial losses in the event of a Hurricane Katrina type event. The timing of natural disasters generally has very little correlation with the economy or financial markets, so purchased in proper quantities, catastrophe bonds can be a good portfolio diversifier.
Another innovation is the so-called “structured note,” an investment product whose return and risk characteristics are very different from an ordinary stock or bond. Large banks and brokerage firms use complex quantitative techniques to engineer these unnatural investments into being and sell them to the investing public. The notes usually offer a deal that sounds attractive, but no amount of financial wizardry can improve the fundamental tradeoff between risk and return.
As an example, a structured note might have a three-year term, over which it pays you the gain of the S&P 500 stock index (if the market goes up), up to a maximum of 25%, and protects you against the first 20% loss on the index (if the market goes down). It’s clear you are giving up some upside return potential for some downside protection, but even very sophisticated investors cannot evaluate whether this is a fair deal. Similarly, it’s nearly impossible to measure the underlying expense the sponsor has built in as compensation for structuring the product. All are reasons to steer clear.
I’ll conclude with an innovation that seems positive for investors, but is at best a mixed blessing. About 10 years ago, upstart broker Robinhood began offering zero-commission stock trading. Eventually, this forced larger competitors like Charles Schwab to follow suit. To make up for lost commission revenue, Schwab now sweeps clients’ idle cash balances into a bank deposit that today pays 0.20% at a time when Schwab’s own money market funds are paying about 4.70%. The spread between the two generates billions of dollars of annual revenue for Schwab, reducing their customers’ returns dollar for dollar.
With every innovation that works to investors’ favor, it seems that the Wall Street empire finds a new way to regain its profits. Stay nimble, and may the force be with you.
Next up is Part III: lessons learned over the past 25 years.
Don Gould is president and chief investment officer of Gould Asset Management of Claremont.
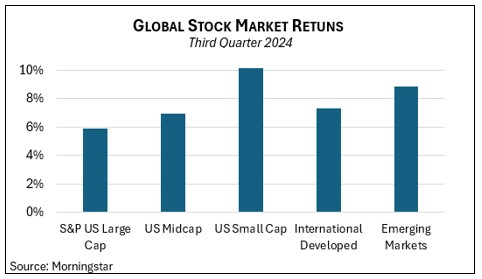
Global stock markets vaulted upward yet again in the third quarter. The S&P 500 US large cap benchmark returned almost 6% and, for a change, US midcap and small cap, international developed, and emerging markets stocks did even better. The S&P 500 closed the quarter up about 22% year to date, matching its 2023 return and bringing its return since the start of last year to nearly 50%. This works out to a 25.5% compound annual rate of return over the last 21 months, which is great but also unsustainable. Over the past century, the US market has averaged just north of 10% per year, a number that many consider optimistic today, with stocks expensive by historical standards.
In September, the Federal Reserve made its long-awaited easing, a hefty 0.50% reduction in short-term interest rates. Combined with continued steady growth in both the economy and corporate profits, investors celebrated by bidding up stock prices worldwide. The S&P 500 and the venerable Dow Jones Industrial Average both hit record highs in September.
Bonds joined the party in the third quarter, with the main US bond index leaping just over 5% and nearly matching the S&P 500. (Declining interest rates push up the price of existing bonds.) The result was a heady quarter for investors across the risk spectrum, with both stocks and bonds shining. For a fuller discussion of the past quarter, be sure to see our Economic and Market Review that accompanies this letter.
Keeping Our Heads
Normally this phrase (from Kipling’s famous poem “If”) refers to difficult times and the challenge of maintaining one’s equilibrium amid turbulence. But for investors, we think the concept equally applies to the best of times, which describes the stock market for most of the last fifteen years and especially 2023 and 2024.
When stocks race higher, there is a natural tendency to expect the trend to continue. It goes against our gut to sell stocks in a rising market. If anything, the apparent uptrend makes investors want to allocate more to stocks. This is the “greed” half of the fear-and-greed cycle.
To keep our heads (and yours), we regularly rebalance portfolios, selling some of the assets that have risen most (lately, that’s stocks), bringing the asset allocation back within a range that reflects our understanding of the client’s tolerance for risk. This discipline is important. When the inevitable market downturn arrives, we want clients in a position that enables them to ride out the storm, rather than having to abandon ship because their portfolio inadvertently became too risky.
Note: This post is an excerpt from Gould Asset Management’s Economic and Market Review for the Third Quarter of 2024. The excerpt is posted here for the benefit of our blog subscribers.
US Consumers Continue Spending, Employers Continue Hiring
US Consumers Continue Spending, Employers Continue Hiring
The US economy accelerated in the second quarter, driven by strong consumer spending. GDP grew at a 3.0% annualized rate in April through June, nearly double its first quarter pace.
The unemployment rate ticked down to 4.1% in September, as employers added over 250,000 jobs last month, the most since March.
Manufacturing activity remained subdued all summer, with weak demand and a slump in hiring. In a sign of potential rebound for the sector, though, new orders increased last month, and input prices fell to a nine-month low.
US home sales fell in August despite the recent decline in mortgage rates. Existing home sales declined 4.1% from a year ago, while the median sale price is up 3.1% over the same period.
Interest Rate Cuts are Here
The Federal Reserve opted for a bold start to its monetary easing, reducing the fed funds rate by 0.50% to a range of 4.75% to 5.00%, its first rate cut since 2020. Fed Chair Jerome Powell stressed that the more aggressive cut is not indicative of a less favorable economic outlook, but rather a decision to support the labor market.
Mr. Powell cautioned that the 0.50% rate cut does not imply a similarly rapid pace of rate cuts going forward. The Fed’s latest forecast shows two additional 0.25% rate cuts this year, aligning with current market expectations. In 2025, the Fed expects to reduce the federal funds rate by another 1.00%.
The Fed’s updated projections also show a slightly weaker labor market in the next year plus, raising their year-end 2024 unemployment forecast from 4.0% to 4.4%, where they expect it to remain through 2025.
As you approach retirement, it is essential to consider how best to manage your retirement assets. For many college professors, these assets are tied to TIAA, a leading provider in higher education retirement plans such as 403(b) plans. Founded over a century ago, TIAA has built a reputation for serving the financial needs of those in academia and other non-profit fields. But what happens to your TIAA retirement assets once you retire? Let’s explore your options.
Understanding Your TIAA Retirement Assets
The first step in planning for your retirement is understanding what you have. Over your career, you may have worked at multiple institutions, each with its own retirement plan under the TIAA umbrella. It’s not uncommon for professors to accumulate multiple accounts, each with different investment options and rules. Therefore, a comprehensive review of your TIAA accounts is critical before making any decisions.
The Options: What Can You Do With Your TIAA Assets?
Once you’ve taken stock of your retirement accounts, you have several options to consider. Each option comes with its own set of pros and cons, and the best choice will depend on your financial goals, the specifics of your TIAA plan, and your comfort level with managing your own investments.
1. Roll Over Some or All of Your Assets Immediately
One option is to roll over some or all of your TIAA assets into another retirement account, such as an IRA. This option provides flexibility in choosing investments outside the TIAA platform, which is particularly appealing if you find the investment options within TIAA limited. Rolling over to an IRA could give you access to a broader range of investment vehicles, including stocks, bonds, and mutual funds.
Special consideration must be taken with accounts invested in TIAA Traditional, a guaranteed annuity product unique to TIAA. Unlike other investments, TIAA Traditional cannot be rolled over as a lump sum. Instead, it must be rolled over in ten equal installments over nine years. A financial advisor can help you determine how best to plan for rolling over your investment in TIAA Traditional.
2. Roll Over Assets Over Time
If you’re not ready to make a full transition out of TIAA or are currently still employed, you can choose to roll over your assets gradually. This approach allows you to continue working while transferring assets from old TIAA plans, gaining access to a broader investment universe with an IRA.
Assets that you don’t want to move or can’t move can be managed by certain advisors without requiring you to move them out of the TIAA platform. This can be an ideal solution if you prefer to keep your assets with TIAA but want professional management to keep your investments aligned with your retirement goals. These advisors can also help manage your TIAA assets in conjunction with other outside assets, providing a holistic approach to your retirement planning.
3. Leave Your Assets at TIAA
Another option is to leave your assets with TIAA. For many, this is the simplest and most straightforward option, especially if you are comfortable choosing your own investments and calling the TIAA customer service phone number when you need assistance.
Leaving your assets with TIAA might also make sense if you want to remain invested in TIAA Traditional or if you’re satisfied with the investment options provided by TIAA and the associated fees they charge.
Final Thoughts: Professional Guidance
As a college professor, you’ve dedicated your career to educating others. Now, as you approach retirement, it’s time to focus on pursuing your ideal financial future. Understanding your TIAA retirement assets and knowing your options are crucial steps in this journey.
Whether you choose to roll over your assets, leave them with TIAA, or gradually transition to a different investment strategy, the most important thing is to make informed decisions that align with your retirement goals. By taking the time to review your options and consulting with knowledgeable advisors, you can confidently navigate this next phase of your life and enjoy the retirement you’ve earned.
That’s where Gould Asset Management can help. Each client comes to our firm with unique circumstances. Age, assets, investment experience, life and financial goals, and risk tolerance are just a few factors. Based on careful consideration, our team crafts unique portfolios for each client.
Johnny DeBiase is Partner and Senior Portfolio Manager at Gould Asset Management, an independent registered investment adviser based in Claremont, California. The firm manages customized portfolios on behalf of individuals, families, and nonprofits, and offers a range of services, including retirement planning, charitable giving strategies, and values-based investment options. As fiduciaries, they always put their clients’ interests first while providing a culture of superior personal service.
With responsibilities including portfolio management, market and investment research, and client relationship management, Johnny enjoys how investing combines numbers and finance with an element of human psychology. A big part of his job involves breaking down complex topics and helping clients tune out the noise to see the big picture. He’s a firm believer that clients come to Gould for the investment advice and stay for the exceptional client service.
Johnny obtained his bachelor’s degree in economics with a minor in chemistry from the University of North Florida and his master’s degree in finance from the Robert Day School of Economics and Finance at Claremont McKenna College. He also holds the Chartered Financial Analyst® (CFA®) designation and is a member of the CFA Institute. In his free time, he enjoys hiking with his wife, Jill, playing with his dogs, Millie and Lola, cooking, practicing yoga, and reading fantasy and sci-fi books. To learn more about Johnny, connect with him on LinkedIn.